Truth in Lending
Understanding Personal Loans Online Lenders
Effective Date: 2026
At SmallPersonalLoansOnline.com, we believe consumers deserve clear, transparent information regarding borrowing costs, repayment obligations, and loan terms before making financial decisions. This Truth in Lending page is designed to help visitors understand important lending concepts and the disclosures that lenders may provide during the application and approval process.
Federal lending laws are intended to promote transparency and help consumers compare financial products more effectively. Understanding these disclosures can help borrowers make informed decisions and avoid unexpected costs.
This page explains common lending disclosures, borrowing terminology, repayment obligations, and consumer rights.
What Is Truth in Lending?
Truth in Lending refers to federal disclosure requirements designed to help consumers understand the cost of borrowing.
These requirements generally encourage transparency regarding:
- Annual Percentage Rate (APR)
- Finance charges
- Repayment schedules
- Total loan costs
- Payment obligations
- Fees and charges
The goal is to help borrowers compare lending products more effectively before accepting financing.
Understanding Personal Loans Online Lenders
Many consumers research Personal Loans Online Lenders because online lending platforms often provide convenient access to loan information and application tools.
Educational resources discussing Personal Loans Online Lenders help consumers understand how digital lending works and what information lenders may disclose during the application process.
Why Lending Disclosures Matter
Borrowing money creates a legal obligation to repay the loan according to agreed terms.
Before accepting financing, consumers should carefully review:
- Interest rates
- Repayment terms
- Monthly payment amounts
- Loan fees
- Total borrowing costs
Understanding these details can help borrowers determine whether a financial product fits their needs and budget.
Important Lending Terms
Annual Percentage Rate (APR)
APR represents the cost of borrowing expressed as a yearly percentage.
APR may include:
- Interest charges
- Certain lender fees
- Financing costs
Consumers often use APR when comparing lending products because it provides a standardized measurement.
Finance Charges
Finance charges represent the total cost of obtaining credit.
These charges may include:
- Interest
- Origination fees
- Certain administrative costs
Total Payment Amount
The total payment amount reflects the full cost of the loan if all payments are made according to schedule.
Understanding Personal Loans Online
The internet has significantly changed the lending industry.
Consumers increasingly research Personal Loans Online because digital platforms often allow borrowers to compare options, review disclosures, and complete applications without visiting physical locations.
Many online lending platforms provide educational resources designed to help consumers understand borrowing obligations before accepting loan offers.
Benefits of Reviewing Disclosures
Reviewing loan disclosures may help consumers:
- Compare offers
- Understand repayment schedules
- Evaluate affordability
- Identify fees
- Calculate total borrowing costs
Informed borrowers are generally better positioned to make responsible financial decisions.
How Loan Payments Work
Most personal loans involve fixed monthly payments.
A payment may include:
- Principal repayment
- Interest charges
- Applicable fees
The exact structure varies depending on lender requirements and loan terms.
Repayment Periods
Common repayment periods may range from:
- Several months
- Multiple years
Longer repayment periods often reduce monthly payments but may increase total borrowing costs.
Shorter repayment periods may result in higher monthly payments while reducing overall interest expenses.
Understanding Personal Loans Credit Union
Many consumers compare lending options offered through banks and Personal Loans Credit Union programs.
Credit unions often operate as member-focused financial institutions and may offer various lending products depending on membership eligibility and qualification requirements.
Educational content regarding Personal Loans Credit Union options can help consumers better understand available borrowing alternatives.
Borrower Responsibilities
Consumers should carefully review all loan documents before signing.
Borrowers are generally responsible for:
- Making payments on time
- Understanding loan terms
- Reviewing disclosures
- Monitoring account activity
- Communicating with lenders regarding payment issues
Failure to meet repayment obligations may have financial consequences.
Potential Consequences of Missed Payments
Missed payments may result in:
- Additional fees
- Collection activity
- Credit reporting impacts
- Increased financial obligations
Borrowers should contact lenders promptly if financial difficulties arise.
Understanding Loan Fees
Some lending products may involve fees.
Examples include:
- Origination fees
- Late fees
- Returned payment fees
- Administrative fees
Consumers should review disclosures carefully to identify all potential costs.
Evaluating Total Cost
Interest rates alone do not always reflect total borrowing costs.
Consumers should review:
- APR
- Fees
- Repayment term
- Total payment amount
These factors collectively influence affordability.
Understanding Personal Loans Interest Rates
One of the most important borrowing considerations involves Personal Loans Interest Rates.
Interest rates influence:
- Monthly payment amounts
- Total borrowing costs
- Overall affordability
Educational resources discussing Personal Loans Interest Rates help consumers understand how borrowing costs are calculated and compared.
Factors That May Influence Rates
Lenders may consider various factors, including:
- Credit history
- Income
- Debt obligations
- Employment information
- Loan amount
- Repayment term
Qualification requirements vary among lenders.
Consumer Rights
Federal and state laws provide various consumer protections.
These protections may include:
- Disclosure requirements
- Fair lending standards
- Complaint procedures
- Privacy protections
Consumers should familiarize themselves with applicable rights before entering financial agreements.
Comparing Loan Offers
Consumers are encouraged to compare multiple offers whenever possible.
Important comparison factors include:
- APR
- Monthly payment
- Repayment term
- Fees
- Total repayment amount
Careful comparison may help consumers identify options that align with their financial goals.
Additional Information About Personal Loans Online Lenders
Consumers researching Personal Loans Online Lenders should carefully review lender disclosures, qualification requirements, and repayment obligations before proceeding with any application.
Different lenders may offer different products and terms.
Internal Resources
Helpful information available on our website includes:
- /about-us
- /contact-us
- /privacy-policy
- /terms-and-conditions
- /advertising-disclosure
- /personal-loan-calculator
- /debt-consolidation-loans
- /bad-credit-loans
Additional Information About Personal Loans Online
Educational resources regarding Personal Loans Online can help consumers better understand application procedures, disclosure requirements, and responsible borrowing practices.
External Resources
Consumers seeking additional information may find these resources useful:
- Consumer Financial Protection Bureau
- Federal Trade Commission
- Federal Deposit Insurance Corporation
- Federal Reserve Consumer Resources
- Annual Credit Report
Additional Information About Personal Loans Credit Union
Consumers evaluating Personal Loans Credit Union offerings should review membership requirements, loan disclosures, and repayment obligations before accepting financing.
Additional Information About Personal Loans Interest Rates
Understanding Personal Loans Interest Rates is essential when comparing loan offers because interest charges may significantly affect total borrowing costs.
Final Truth in Lending Statement
At SmallPersonalLoansOnline.com, we believe transparency and education help consumers make better financial decisions. Borrowers should carefully review all disclosures, understand repayment obligations, compare multiple offers, and evaluate affordability before accepting financing.
Responsible borrowing begins with understanding the full cost of credit, including interest rates, fees, repayment terms, and total payment obligations.
Affiliate Disclosure: We are an affiliate marketing website and may receive compensation from lending partners. We are not a lender, do not make credit decisions, and do not guarantee approval. Loan terms and rates are determined by individual lenders.
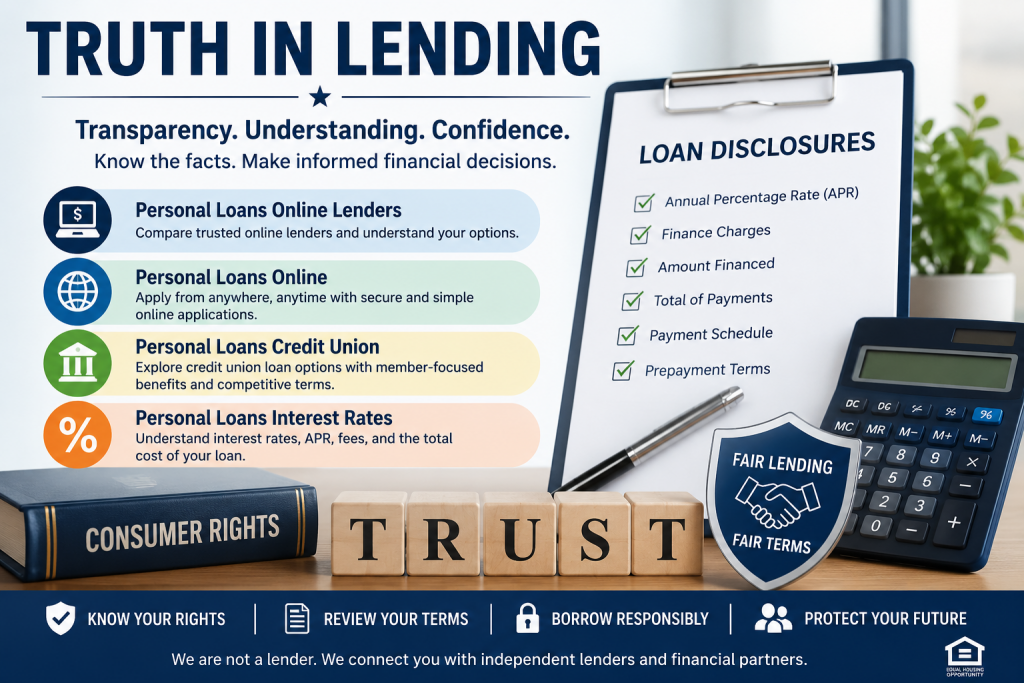
Truth in Lending: Understanding Online Personal Loan Lenders, Credit Unions, and Interest Rates
1. Understanding Your Rights Before Borrowing
Borrowing money can help consumers manage necessary expenses, consolidate debt, or cover unexpected financial obligations. However, obtaining financing also creates a legal responsibility to repay the principal, interest, and applicable charges according to the agreement.
The federal Truth in Lending Act, commonly known as TILA, promotes informed borrowing by requiring covered creditors to disclose important credit costs and terms. Its implementing regulation, Regulation Z, establishes detailed disclosure requirements for different types of consumer credit.
When researching Personal Loans Online Lenders, consumers should identify the actual creditor, determine how the application works, and review written financing disclosures before accepting an offer.
Many websites advertise Personal Loans Online with convenient applications and electronic signatures. Convenience can be useful, but a fast application does not necessarily mean the loan is inexpensive.
Consumers comparing Personal Loans Credit Union products may find member-focused financial institutions that offer installment financing, financial education, and personal customer assistance.
Understanding Personal Loans Interest Rates is equally important because interest charges affect monthly payments and the total cost of borrowing.
At SmallPersonalLoansOnline.com, we provide educational resources about personal borrowing and lender comparisons.
Before borrowing, calculate the amount actually needed, evaluate alternative payment arrangements, and establish a realistic household budget. A responsible financing decision should address a genuine financial need without creating unnecessary long-term debt.
2. What Federal Lending Disclosures Explain
The Truth in Lending framework helps consumers understand the cost of credit before becoming contractually obligated. For covered closed-end loans, required disclosures generally include the annual percentage rate, finance charge, amount financed, total of payments, and payment schedule.
Consumers evaluating Personal Loans Online Lenders should ask for disclosures showing the actual terms offered to them rather than relying exclusively on promotional advertisements.
Websites marketing Personal Loans Online may display estimated rates that change after credit, income, and identity verification. An initial estimate should not be confused with a final agreement.
Borrowers considering Personal Loans Credit Union financing should also examine written disclosures carefully. Membership-based institutions must still comply with applicable federal and state lending requirements.
Comparing Personal Loans Interest Rates involves distinguishing between the stated interest rate and the APR, which incorporates certain finance charges into an annualized measure of borrowing costs.
The Consumer Financial Protection Bureau’s Regulation Z guidance describes the disclosures required for covered closed-end credit transactions.
The amount financed generally represents the net amount of credit provided under the applicable disclosure rules. The finance charge represents the dollar cost of credit, including interest and certain fees.
The total of payments reflects what the borrower is scheduled to pay under the agreement.
Consumers should also review provisions covering late payments, default, automatic withdrawals, and prepayment.
If a contract contains confusing language, request clarification before signing. Written disclosures help borrowers make meaningful comparisons, but understanding the full agreement remains essential.
3. Comparing Online Lenders and Financial Marketplaces
The Truth in Lending requirements apply to covered consumer credit transactions regardless of whether the application begins at a branch, on a website, or through a mobile device.
Consumers exploring Personal Loans Online Lenders may encounter banks, credit unions, nonbank finance companies, and referral platforms. These businesses do not necessarily perform the same role.
Some websites advertising Personal Loans Online collect consumer inquiries and forward information to participating financial institutions. Others originate financing directly and service the resulting accounts.
Consumers considering Personal Loans Credit Union services should determine whether membership is required before applying and whether the institution serves their geographic area or professional community.
When evaluating Personal Loans Interest Rates, compare actual offers from multiple credible institutions using similar loan amounts and repayment periods.
A marketplace may provide access to several potential lenders, but submitting an inquiry does not guarantee that multiple offers will be available.
Before providing personal information, identify the legal creditor and read the website’s privacy policy.
Ask whether information will be shared with marketing partners, whether preliminary qualification involves a soft credit inquiry, and whether a formal application authorizes a hard inquiry.
Banks and credit unions may appear in different regulatory directories.
A reputable financing process should provide clear information about lender identity, borrowing costs, repayment obligations, and customer service.
4. Understanding Credit Union Personal Loan Financing
The Truth in Lending rules help establish consistent disclosure standards, but individual financial institutions may offer different loan amounts, repayment terms, and underwriting requirements.
When comparing Personal Loans Online Lenders, borrowers should consider whether a traditional bank, credit union, or nonbank lender provides the most appropriate combination of costs and services.
Applications for Personal Loans Online may offer electronic document submission and account management, while local institutions may provide additional in-person assistance.
Consumers exploring Personal Loans Credit Union financing should investigate membership eligibility, account requirements, and available installment products.
Comparing Personal Loans Interest Rates across credit unions and other lenders can help consumers understand whether a particular offer is competitive for their credit profile.
Credit unions are cooperative financial institutions that serve eligible members. Some are federally chartered, while others operate under state charters.
The National Credit Union Administration regulates federal credit unions and administers federal share insurance for eligible accounts.
For most loans made by federal credit unions, the NCUA has extended a temporary 18% interest-rate ceiling through September 10, 2027. Certain qualifying payday alternative loans have a separate maximum rate under NCUA regulations.
That ceiling is not a universal rate limit for every state-chartered credit union, bank, or nonbank lender.
Membership requirements may depend on location, employment, family relationships, or participation in qualifying organizations.
Borrowers should compare APR, fees, payment flexibility, customer support, and the total amount payable.
Credit unions can be valuable financing sources, but no particular institution is automatically the best choice for every applicant.
5. How Interest Rates Affect Monthly Payments
The Truth in Lending disclosure process makes it easier to compare credit costs, but borrowers should also understand how interest accumulates throughout a repayment period.
When researching Personal Loans Online Lenders, request individualized offers rather than assuming that advertised starting rates are available to everyone.
Advertisements for Personal Loans Online may feature attractive monthly payments without emphasizing the total amount of interest paid over several years.
Consumers reviewing Personal Loans Credit Union offers should examine whether the proposed rate is fixed or variable and whether membership-related conditions affect pricing.
Understanding Personal Loans Interest Rates helps borrowers evaluate the financial tradeoffs between different APRs, loan amounts, and repayment durations.
Consider a hypothetical $5,000 installment loan repaid over 36 months without additional fees.
At 6% fixed annual interest, the monthly payment is approximately $152.11, with roughly $476 in total interest.
At 12%, the payment increases to approximately $166.07, with roughly $979 in interest.
At 18%, the payment rises to approximately $180.76, producing about $1,507 in interest.
These examples are mathematical illustrations, not actual offers or promises of available rates.
Origination fees can further increase borrowing costs. If a lender deducts a $250 fee from a $5,000 principal, the borrower might receive $4,750 while remaining obligated to repay the contractual principal.
A longer repayment period may lower monthly payments but increase total interest.
Compare both monthly affordability and the complete repayment obligation before accepting financing.
6. Credit Scores, Income, and Loan Eligibility
The Truth in Lending Act establishes important disclosure obligations, but it does not require creditors to approve every application or offer identical financing terms to all borrowers.
Applicants evaluating Personal Loans Online Lenders should understand that underwriting standards can vary considerably between institutions.
Some providers advertising Personal Loans Online offer preliminary prequalification that may involve a soft credit inquiry. Completing the application can still result in a hard inquiry.
Consumers researching Personal Loans Credit Union products may need to establish membership and provide documentation of income, employment, identity, and existing obligations.
Differences in Personal Loans Interest Rates can reflect credit history, repayment duration, requested principal, and other risk factors considered by the creditor.
Review payment histories, balances, unfamiliar accounts, and potentially inaccurate information.
If you discover an error, dispute it with the credit reporting agency and the organization that supplied the information.
Lenders may also consider the relationship between monthly debt obligations and income.
A borrower with significant existing payments may have difficulty qualifying for additional financing, even with a reasonable credit score.
Avoid submitting unnecessary formal applications when preliminary comparisons can provide useful information.
No credit score guarantees approval, and advertised rates may not reflect the final terms offered.
The appropriate borrowing amount is one that meets a legitimate need while remaining affordable throughout the repayment period.
7. Recognizing Loan Fees and Contractual Obligations
The Truth in Lending requirements help consumers identify credit costs, but borrowers must also review contractual provisions that may affect their finances after the agreement begins.
Consumers comparing Personal Loans Online Lenders should ask about origination fees, late-payment charges, optional insurance products, and payment processing arrangements.
Websites advertising Personal Loans Online should clearly distinguish promotional information from the actual terms offered by the creditor.
Borrowers reviewing Personal Loans Credit Union agreements should also determine whether any account or membership requirements involve separate charges.
Evaluating Personal Loans Interest Rates without considering fees can produce an incomplete comparison of total borrowing costs.
An origination fee may be deducted from the proceeds, reducing the cash available to the borrower.
A late fee may apply when a scheduled installment is not received according to the agreement.
Missed payments can also affect credit reporting and may lead to collection activity.
Ask whether the loan has a prepayment penalty or restrictions on additional principal payments.
Review automatic withdrawal authorizations to understand when funds will be collected and how payment methods can be changed.
For variable-rate products, determine how and when the interest rate may change.
The CFPB’s consumer education resources explain borrowing terminology and provide guidance for evaluating financial products.
Keep copies of all disclosures, contracts, and payment confirmations.
If the lender’s final offer differs from the preliminary estimate, compare alternatives before accepting.
The most useful agreement is one whose obligations are clear, reasonable, and compatible with the borrower’s budget.
8. Avoiding Misleading Loan Advertising and Financial Scams
The Truth in Lending framework supports transparent credit disclosures, but consumers must still investigate suspicious advertisements and unfamiliar financial businesses.
Websites claiming to represent Personal Loans Online Lenders should identify the actual creditor and provide reliable contact information.
Advertisements promoting Personal Loans Online may promise rapid decisions, but consumers should be cautious when a company guarantees approval regardless of financial circumstances.
Someone exploring Personal Loans Credit Union financing should verify that the organization is a legitimate institution and that the advertised offer comes from its official website.
Claims about Personal Loans Interest Rates can be misleading when an advertisement emphasizes an unusually low rate without explaining eligibility requirements or applicable fees.
The Federal Trade Commission warns consumers about advance-fee loan scams involving promised financing that never materializes.
Warning signs include demands for gift cards, cryptocurrency, suspicious wire transfers, or unusual upfront payments to release supposedly approved funds.
A properly disclosed origination fee is different from sending money to an unknown person who promises guaranteed approval.
Do not provide banking passwords to unfamiliar individuals or submit identification documents through unsolicited messages.
Verify the creditor’s legal name and investigate relevant licensing information independently.
A professional-looking website or positive testimonial does not automatically establish legitimacy.
Consumers who suspect fraud can report it through ReportFraud.ftc.gov.
Protecting existing savings and personal information is more important than obtaining financing immediately.
9. Making an Informed Personal Loan Decision
The Truth in Lending Act provides an important foundation for informed borrowing, but consumers must ultimately decide whether a proposed agreement fits their financial circumstances.
Before choosing among Personal Loans Online Lenders, compare the legal creditor, APR, fees, repayment schedule, and total amount payable.
Consumers exploring Personal Loans Online should understand whether the website originates financing directly or operates as an educational or referral platform.
Applicants considering Personal Loans Credit Union services should evaluate membership requirements, available products, customer support, and individualized financing terms.
Comparing Personal Loans Interest Rates is most useful when offers involve similar principal amounts and repayment periods.
Prepare a monthly household budget that includes housing, groceries, utilities, transportation, insurance, existing debts, and emergency savings.
Determine whether the new installment would remain manageable during a temporary reduction in income.
Consider alternatives such as savings, creditor payment arrangements, or available assistance programs before borrowing for urgent expenses.
If the proposed payment would require sacrificing essential necessities, investigate a smaller amount or another solution.
At SmallPersonalLoansOnline.com, we publish educational information about borrowing and may receive advertising or referral compensation.
We are not a direct lender or loan broker, do not make credit decisions, and cannot guarantee approval, interest rates, loan amounts, or funding times.
Consumers should verify lender authorization in their state and read all financial disclosures before signing.
Responsible borrowing begins with transparent information, realistic budgeting, and a clear understanding of repayment obligations.